By Adnan Adams Mohammed
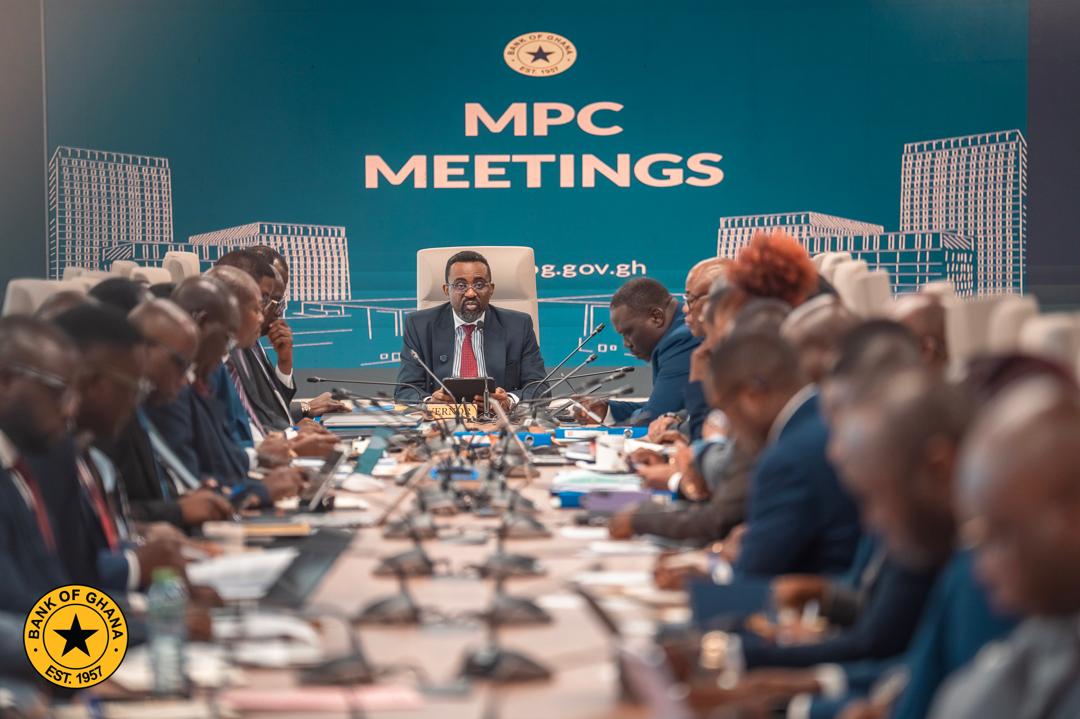
The Bank of Ghana (BoG) has reset its benchmark Monetary Policy Rate (MPR) to 11 percent, a 300-basis-point reduction from 14%, capitalizing on favorable domestic macroeconomic conditions, robust economic expansion, and declining money market rates.
Announcing the policy reset in Accra on today Wednesday, November 18, 2026, at the close of the 133rd Monetary Policy Committee (MPC) meetings, BoG Governor Dr Johnson Pandit Asiama said the decision aligns the central bank’s policy benchmark with prevailing market realities while cementing conditions for sustained private-sector-led growth.
“Taken together, the Committee noted significant improvements in domestic macroeconomic conditions,” Dr Asiama stated at the press briefing. “Domestic growth has remained firm, supported by easing credit conditions and expansion of private sector credit, and is expected to continue for the remainder of the year.”
Recalibrating the Monetary Operations Framework
Rather than a routine rate cut, the central bank framed the move as a broader reset of its monetary operations architecture. Because earlier operational adjustments had already pulled money market rates below the previous 14% benchmark, the MPC moved to eliminate the disconnect between its announced rate and actual market conditions.
To sharpen liquidity management and tighten policy transmission, the BoG replaced its existing 14-day Open Market Operations (OMO) instrument with a seven-day instrument and narrowed the monetary policy corridor from plus or minus 400 basis points to plus or minus 100 basis points around the new 11% rate.
“Recent reforms to the Bank’s monetary operations framework have strengthened liquidity management and improved the transmission of monetary policy signals to money market rates,” Dr Asiama explained. “As a result, prevailing market rates have evolved at levels below the current monetary policy rate, indicating that the effective policy stance is actually lower than the announced rate.”
Macroeconomic Tailwinds Backing the Reset
The policy reset is anchored by strong performance across key domestic indicators:
Surging Economic Momentum: The BoG’s updated Composite Index of Economic Activity (CIEA) expanded by 17.7% year-on-year in September 2026, nearly doubling the 9.6% growth recorded in September 2025, driven by construction, export performance, and increased business lending.
Falling Borrowing Costs: Between October 2025 and October 2026, the benchmark 91-day Treasury bill rate plunged from 10.6% to 4.6%, pulling average commercial bank lending rates down from 22.2% to 15.8%.
Private Sector Credit Boom: Supported by cheaper borrowing costs, annual private sector credit growth jumped to 37.2% in October 2026 from 13.9% a year earlier, representing a 30.0% expansion in real terms compared to 5.4 per cent in the prior period.
Fiscal Discipline: Provisional data for the first ten months of 2026 showed an overall fiscal deficit of 1.0% of Gross Domestic Product (GDP)—well below the 3.0% ceiling—alongside a primary surplus of 1.4% of GDP, keeping the government on track to meet its full-year target of 1.5% through expenditure discipline and prudent debt management.
Inflation Outlook and External Buffers
Favorable price stability further gave the Committee room to reset its stance. Although headline inflation edged up marginally to 5.5% in October 2026 from 5.2% in September—driven by non-food inflation rising to 7.9% on utility tariffs and crude oil costs—it remains comfortably below the lower band of the central bank’s medium-term target. Improved domestic food supplies also pushed food inflation down to 2.8% from 4.0%.
While inflation expectations among consumers, businesses, and banks remain firmly anchored, the MPC noted that future price stability will require monitoring risks from crude oil volatility, potential El Niño weather impacts on agriculture, and scheduled quarterly utility tariff adjustments.
On the external front, resilient export receipts continued to support the economy, though higher external debt service obligations and foreign exchange demand moderated gross international reserves to US$12.1 billion (4.4 months of import cover) as of November 17, 2026, compared with US$13.8 billion (5.7 months of import cover) at the end of December 2025.
The Monetary Policy Committee is scheduled to reconvene for its next policy assessment in January 2027.
