By Adnan Adams Mohammed
Ghana has taken a decisive step toward transforming its financial sector by tapping into the rapidly growing global non-interest finance market, projected to reach $10.5 trillion by 2030.
The bold regulatory move was unveiled during the 5th Non-Interest Finance International Conference on November 7, 2026, where the Bank of Ghana announced it is reviewing three full license applications to launch non-interest commercial banking institutions in the country.
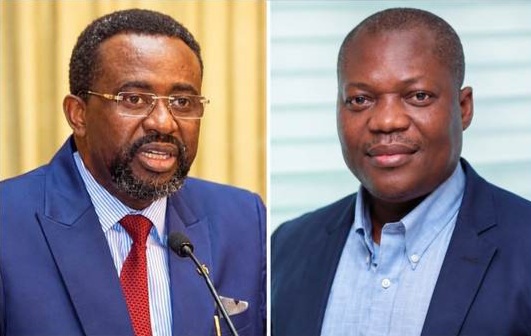
Delivering an address on behalf of Bank of Ghana Governor Dr. Johnson Pandit Asiama, Bank Advisor Prof. John Gatsi outlined how the central bank is creating a forward-looking, asset-backed financial ecosystem aimed at driving real economic growth, SME expansion, and national infrastructure.
Positioning Ghana as a West African Financial Hub
By introducing a comprehensive supervisory regime that aligns central bank policies with the National Insurance Commission and the Securities and Exchange Commission (SEC), Ghana is positioning itself to capture international investment via non-interest bonds (Sukuk) and ethical financial instruments.
“Global sukuk issuance reached approximately US$291.4 billion in 2025 and is projected to continue growing in the coming years,” Dr. Asiama noted in the address. “Ghana must join the beneficiaries of non-interest financing instruments for the expansion of strategic infrastructure of the country.”
The Governor emphasized that while several international jurisdictions launched operations without structured regulatory oversight, Ghana deliberate approach has created a robust framework admired by regional peers.
“As a result of sound regulatory framework, the Bank has received three licence applications, which are currently under rigorous review and consideration,” the address confirmed.
A Commercial Tool for Unlocking Idle Capital
Beyond high-level capital markets, the storyline centers on unlocking capital from unbanked households and small businesses burdened by conventional interest rates. Bank of Ghana officials emphasized that non-interest banking is built on commercial, risk-sharing principles designed to mobilize dormant funds across the country.
“Non-interest banking attracts individuals and businesses that may be excluded from conventional banking due to interest burden and personal preferences,” Dr. Asiama stated. “Our non-interest banking model is to contribute hugely to financial inclusion to improve complementary access to financing in the interest of the economy.”
Addressing the fundamental mechanics of the framework, the Central Bank made clear that the model operates as a viable, profit-driven enterprise rooted in ethical stewardship and real-economy investments.
“Non-interest banking is a commercial banking designed to serve its clientele to make profit,” Dr. Asiama added. “We firmly believe that, when properly implemented, non-interest banking can complement the conventional financial system, broaden access to financial services, mobilise productive investment, deepen financial inclusion, and contribute meaningfully to Ghana’s socio-economic transformation.”
