By Adnan Adams Mohammed
Ghana’s broader macroeconomic framework is exhibiting signs of steady monetary direction, even as persistent banking sector risks and rising construction material costs create localized inflationary pressures.
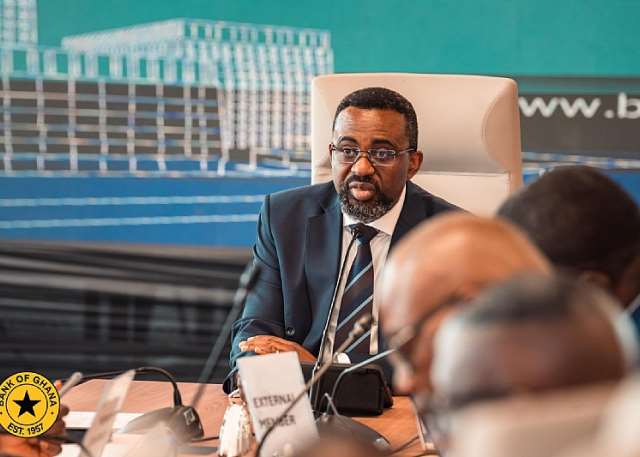
In its latest economic assessment, Fitch Solutions reaffirmed its projection that the Bank of Ghana will hold its monetary policy rate at 14.00% through December 2026.
Looking further ahead, the research firm expects the central bank to adjust rates upward to 16.00% in 2027 to address shifting inflation trajectories. Fitch estimates that headline consumer inflation will average 4.7% in 2026 before rising to an average of 11.3% in 2027.
Banking Sector Strains Persist
Despite the steady interest rate environment, S&P Global has warned that structural vulnerabilities within the financial sector could constrain broader economic momentum, singling out the industry’s elevated Non-Performing Loan (NPL) ratio.
The credit rating agency highlighted that unresolved non-performing assets continue to tie up capital and limit dynamic private sector lending across major commercial institutions.
“The banking sector’s Non-Performing Loan ratio of 16.1% as of June 2026 is considered to be too high,” S&P Global stated in its analysis, noting that credit risk remains a dominant factor for local lenders.
Real Estate and Infrastructure Cost Pressures
Adding to sector-specific inflation, data from the Ghana Statistical Service shows rising cost pressures within the domestic building and civil engineering industries.
The Prime Building Cost Index for August 2026 reached 4.6% year-on-year, up from 4.0% in July. GSS metrics indicate that while core inputs like cement and basic labor remained relatively flat, higher operational charges and equipment hire costs drove the month-on-month increase.
Together, these indicators point to a macroeconomic environment defined by steady monetary policy management alongside targeted cost challenges in real estate, construction, and banking asset recovery.
